
By Logan Parker September 26, 2026
The best keyed transaction lower interchange settings are not one magic checkbox. Better card-not-present qualification generally comes from accurate address data, valid enhanced commercial-card data, correct transaction and stored-credential indicators, proper authorization, and timely clearing. Which fields matter depends on the network, card product, merchant category, transaction type, and processor implementation.
For merchants processing meaningful manually entered volume, keyed transaction lower interchange settings should be treated as a transaction-quality system rather than a simple virtual-terminal preference.
The objective is to capture the information required for the applicable transaction, classify it correctly, and submit it within the relevant authorization and clearing rules.
A virtual terminal can make those controls routine—or leave them optional and create preventable downgrades. Mastercard states that interchange qualification can depend on factors including merchant category, authorization-to-clearing time, enhanced transaction data, and other program criteria.
Mastercard interchange criteria and current rate resources Visa likewise publishes separate card-not-present, commercial, EIRF, Standard, and other interchange programs rather than one universal “keyed rate.”
Virtual Terminal Qualification Settings Summary
| Setting or Field | Why It Matters | Transactions Affected | Common Failure |
| Billing ZIP / address | Supports AVS and complete CNP authorization data | Many CNP transactions | Missing or inaccurate address |
| CVV/CVC/CID | Strengthens initial CNP authorization and fraud screening | Appropriate one-time CNP transactions | Not requested, or improperly stored |
| Invoice/order number | Reconciliation and enhanced-data usefulness | B2B and processor-specific workflows | Blank or placeholder value |
| Sales tax amount | Part of enhanced commercial-card data | Eligible commercial transactions | Missing or fabricated amount |
| Customer code | Commercial-card accounting data | Eligible commercial workflows | Not captured |
| Item-level data | Supports enhanced commercial-card processing | Eligible Level III-type workflows | Incomplete or invalid line items |
| Transaction type | Identifies how the payment should be processed | MOTO, recurring, stored credential, e-commerce | Generic keyed-sale coding |
| Batch timing | Helps preserve authorization/clearing qualification | Many interchange programs | Transactions left unsettled |
| Stored-credential indicators | Correctly classifies repeat charges | Recurring and credential-on-file transactions | Re-keying the PAN as a new sale |
These controls matter most when a merchant can actually see interchange categories separately from processor markup. A useful background reference is Lowest Rate Payments’ explanation of how tiered, flat-rate, and interchange-plus pricing differ.
That distinction becomes important later when identifying whether higher costs are coming from transaction qualification or from the processor’s own pricing.
Why Keyed and Card-Not-Present Transactions Cost More
Keyed transactions often cost more because typing a card number usually means the payment lacks the physical-card evidence available in an EMV chip transaction. But the applicable card not present interchange requirements involve more than the fact that someone typed a PAN.
A keyed transaction at a physical terminal, true mail-order/telephone-order transaction, e-commerce payment, virtual-terminal sale, initial credential-on-file transaction, and subsequent recurring merchant-initiated transaction can follow different authorization and qualification paths.
Mastercard’s current U.S. interchange materials demonstrate this distinction by publishing different programs and qualification criteria instead of treating all manually entered payments identically.
The issue is therefore not simply “keyed versus dipped.” Transaction environment, authorization data, commercial-card information, stored-credential status, and clearing behavior can all matter.
This is also why two businesses with similar monthly card volume can have very different effective processing costs.
Transaction mix—including card type and whether payments are card-present or card-not-present—can materially change the underlying cost structure, as explained in this overview of how card type, transaction method, and industry affect processing costs.
What Separates a Qualified CNP Transaction From a Downgrade?
Interchange qualification means a transaction satisfies the criteria for a particular network interchange program. Failing a relevant criterion can result in the transaction being assigned to another program with different economics.
Potential causes include:
- Missing authorization or transaction data
- Authorization-to-clearing timing problems
- Incorrect transaction-environment indicators
- Missing or invalid enhanced commercial-card data
- Incorrect stored-credential classification
- Merchant-category or product ineligibility
- Failure to meet network-specific card not present interchange requirements
Mastercard expressly explains that its interchange criteria can include merchant category, time between authorization and clearing, presence or absence of certain card data, enhanced transaction data, and transaction volume.
Terms such as EIRF, Standard, Merit, Data Rate, or processor-created “non-qualified” descriptions should therefore be interpreted in their network and card-product context. They are not interchangeable names for every expensive transaction.
For merchants trying to implement keyed transaction lower interchange settings, this distinction matters: configuration should be based on the qualification path actually supported by the network, processor, gateway, and card product—not on a generic claim that “more fields always mean a lower rate.”
The Virtual Terminal Fields That Matter Most
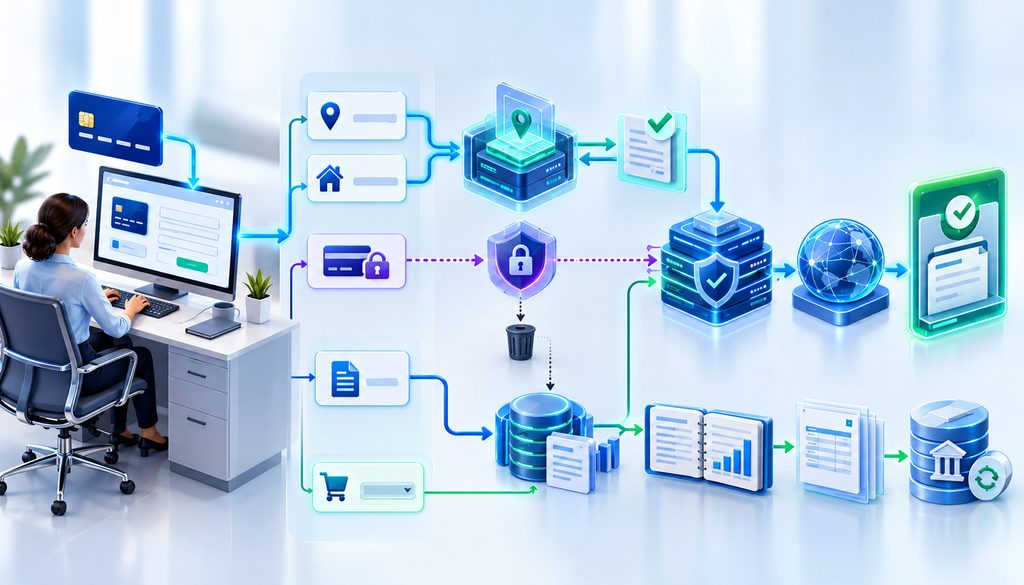
The right configuration makes useful fields part of the payment workflow instead of depending on employees to remember them.
| Field | Operational Purpose | Qualification Impact | Required for All Cards? | Staff Rule |
| Billing ZIP | AVS input | Can matter in applicable CNP paths | No universal rule | Require when supported and appropriate |
| Street address | Fuller AVS information | Network/product dependent | No | Capture accurately |
| CVV/CVC/CID | Initial CNP fraud verification | Primarily authorization/fraud control | No | Collect appropriately; never retain |
| Invoice/order number | Reference and reconciliation | Can support enhanced/commercial data | No | Use real transaction reference |
| Sales tax | Commercial enhanced data | Relevant to eligible products | No | Enter actual amount only |
| Customer code | B2B accounting reference | Relevant to eligible commercial products | No | Require in applicable B2B workflow |
| Item detail | Enhanced transaction data | May support eligible commercial programs | No | Validate totals and line data |
| Transaction type | Correct processing classification | Potentially material | Conceptually yes | Never default every payment to generic keyed sale |
| Stored-credential indicator | Identifies repeat-payment framework | Material to credential-on-file handling | Stored-card transactions | Use supported gateway logic |
Billing ZIP Code
Billing ZIP is commonly submitted into Address Verification Service processing. Mastercard describes AVS as an authorization service that compares supplied billing-address information as part of fraud prevention and cardholder verification.
That makes ZIP valuable, but AVS match interchange qualification is conditional. Supplying address information can be part of the applicable CNP data set, yet an AVS match does not automatically produce lower interchange for every network, merchant category, and card product.
Street Address
Where the virtual terminal and processor support full AVS, accurate street-address information can provide a stronger address comparison than ZIP alone.
Do not train staff to type fake street numbers or recycle a generic billing address. The objective is accurate authorization data, not merely making a required field pass validation.
CVV / CVV2 / CVC2 / CID
Card verification codes can be requested for appropriate card-not-present authorizations to help verify that the customer possesses the card.
PCI SSC classifies these values as sensitive authentication data and states that card verification codes cannot be retained after authorization—even when encrypted.
Configure the terminal to request CVV where appropriate for an initial CNP transaction, but never save it for future recurring or card-on-file charges.
CVV is primarily a fraud and authorization control. It should not be presented as a universal shortcut to lower interchange.
Virtual Terminal Invoice Number Field
The virtual terminal invoice number field is useful because it connects the payment to the underlying customer invoice, order, job, or accounts-receivable record.
Gateways may expose this data under different labels, including invoice number, order ID, purchase-order number, or customer reference. Whether a particular field becomes a meaningful network data element depends on how the gateway and processor map it downstream.
For accounting teams, making the virtual terminal invoice number field mandatory can also prevent orphaned payments that are difficult to reconcile. Use the real invoice or order reference rather than “N/A,” “0000,” or the same placeholder on every transaction.
Sales Tax Amount
Sales-tax information becomes especially important in eligible commercial-card enhanced-data workflows.
The value should reflect the actual transaction. If tax is legitimately zero, submit the appropriate legitimate zero-tax treatment supported by the processor. Never invent a sales-tax value simply to attempt to reach another interchange category.
Customer Code / PO Number
A customer code is typically a buyer-defined accounting reference. Depending on the corporate customer, it could represent a cost center, department, project, purchase order, or general-ledger identifier.
For B2B merchants, the operational control is straightforward: expose the customer-code or PO field to the accounts-receivable users who need it and make it mandatory where the customer or eligible commercial-card workflow calls for it.
Item-Level Data
Enhanced Level III-style information goes beyond the transaction total. Depending on the applicable network and commercial program, line-item records can include information such as:
- Product or SKU code
- Item description
- Quantity
- Unit cost
- Line-item tax
- Freight
- Discounts
- Order information
- Invoice references
- Other product-specific data
Ordinary consumer cards do not automatically receive lower interchange because a clerk fills in Level III fields. Commercial-card eligibility and proper downstream transmission still matter.
AVS Match and Interchange Qualification
AVS match interchange qualification should be understood as three separate events rather than one automatic rate decision:
- AVS data submitted — the billing address or ZIP transmitted with authorization.
- AVS response received — the issuer/network response to that comparison.
- Interchange qualification — the interchange program under which the cleared transaction ultimately qualifies.
AVS is fundamentally an address-verification and fraud-control mechanism. Address information can also be relevant to particular card not present interchange requirements, but a successful match is not a universal interchange discount.
Likewise, an address mismatch does not automatically mean every payment must be declined. A merchant’s fraud policy can evaluate AVS alongside transaction amount, customer history, transaction type, other authentication signals, and business-specific risk.
This distinction is central to good keyed transaction lower interchange settings. Require accurate address information because it improves transaction quality and supports applicable qualification paths—not because staff have been told that “ZIP always lowers the rate.”
Which Commercial-Card Fields Can Lower Interchange?
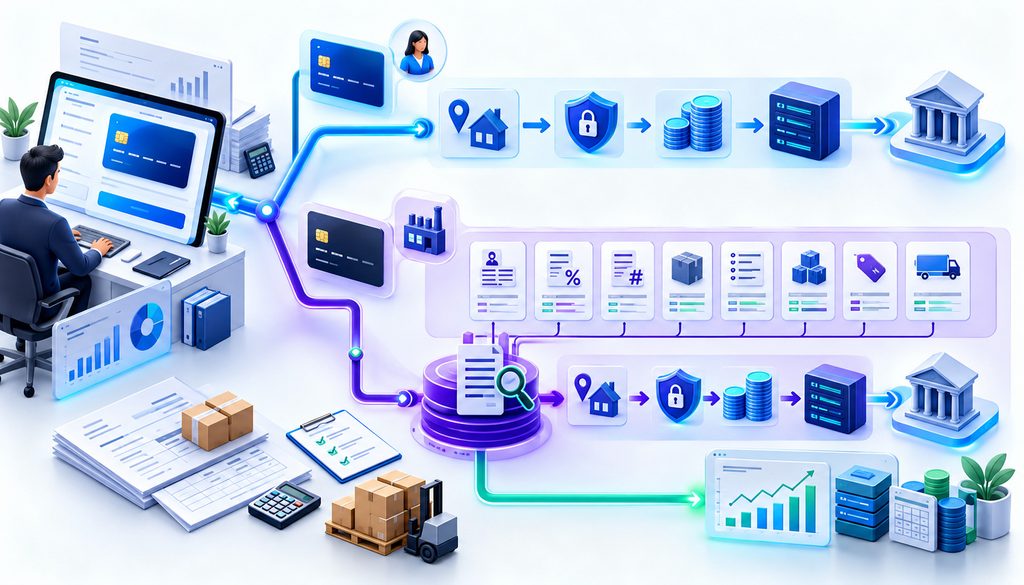
Commercial cards deserve a separate workflow because enhanced-data opportunities differ from ordinary consumer-card qualifications.
Consumer Cards
For an ordinary consumer card, filling customer-code, tax, purchase-order, and detailed line-item fields does not automatically unlock commercial-card interchange programs.
The merchant should still submit accurate CNP authorization data, choose the correct transaction environment, and clear the transaction properly.
Commercial Cards
Business, purchasing, corporate, government, and other commercial products can have different interchange qualification paths.
Mastercard’s published interchange schedules include commercial data programs, while Visa maintains separate commercial-card programs within its U.S. interchange schedules.
Consumer vs. Commercial Card Data
| Data | Consumer Card | Eligible Commercial Card |
| Billing address / ZIP | Useful CNP authorization data | Useful CNP authorization data |
| CVV at initial sale | Fraud/authentication control | Fraud/authentication control |
| Invoice/order reference | Reconciliation | Can also support enhanced data |
| Customer code | Usually no commercial-data benefit | Potentially relevant |
| Sales tax | Normal transaction accounting | Potentially relevant enhanced data |
| Item-level detail | Usually no commercial-data benefit | Potentially relevant Level III data |
| Stored-credential indicator | Relevant when credential is stored | Relevant when credential is stored |
The virtual terminal must actually map these fields through the gateway, processor, and network. A box appearing on-screen does not prove that the required downstream data element is being transmitted correctly.
Same-Day Batch Settlement Rates and Qualification Timing
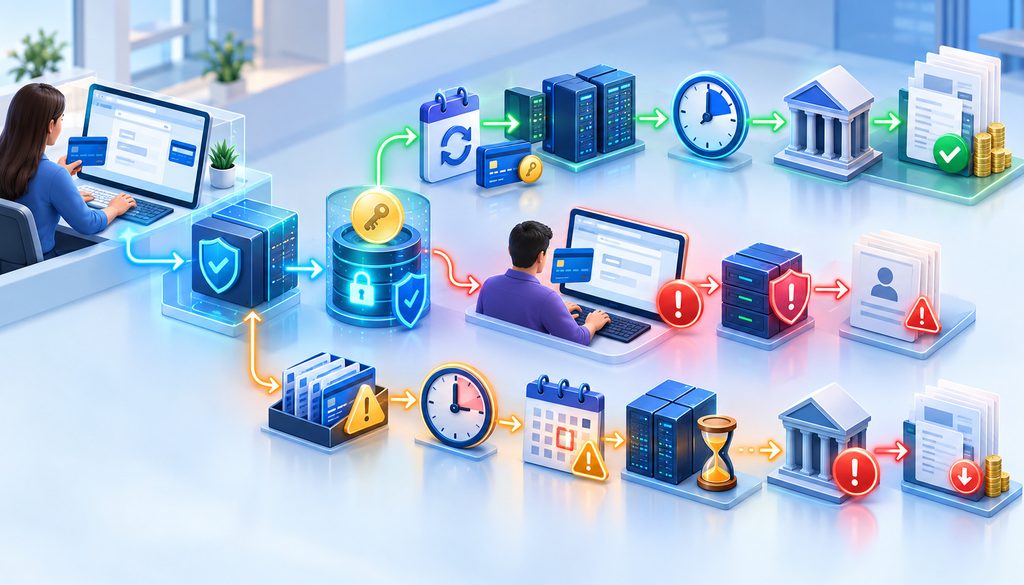
The phrase same day batch settlement rates is useful when researching this topic, but technically it requires qualification. Same-day batching does not universally guarantee the lowest interchange rate.
Authorization occurs first, followed by clearing and settlement. Mastercard identifies the time between authorization and clearing as one of the criteria that can influence interchange qualification.
Network rules can also impose different timing expectations according to transaction type and authorization circumstances. Mastercard’s transaction rules demonstrate why merchants should not reduce this subject to one universal “settle within X hours” claim.
Batch Timing and Qualification Risks
| Operational Pattern | Risk |
| Nightly automatic batch | Reduces forgotten-settlement risk |
| Manual close every evening | Depends on employee discipline |
| Batch repeatedly left open | Can age authorizations unnecessarily |
| Weekend behavior unknown | Transactions may sit longer than intended |
| Wrong terminal timezone | Cutoff may occur unexpectedly |
| Capture delayed after authorization | May affect qualification depending on program |
| Authorization reused too long | Can create authorization/clearing problems |
A well-configured auto-batch is therefore one component of keyed transaction lower interchange settings, but merchants should distinguish the processor’s daily cutoff from the network’s underlying qualification rules.
How to Configure Auto-Batch So Staff Cannot Forget
- Determine the processor/acquirer cutoff time: Do not assume it is the same thing as a network qualification deadline.
- Configure automatic daily batch close: High-volume merchants should not depend on somebody remembering a manual button.
- Leave operational margin before the cutoff: Avoid scheduling the close at the final possible minute.
- Verify the terminal timezone: A portal running in another timezone can settle later than employees expect.
- Test weekend and holiday behavior: Determine whether weekend activity automatically closes or carries forward.
- Ask what happens to unsettled transactions: Confirm whether they remain in an open batch, require intervention, or eventually expire.
- Run a controlled live transaction: Confirm authorization, capture, batch close, and settlement reporting.
- Review the settlement record: Verify that the actual clearing date matches the intended configuration.
For a high-volume MOTO merchant, this operational discipline matters more than chasing a vague promise about same day batch settlement rates.
Make Required Fields Mandatory, Not Optional
Training is helpful. System enforcement is stronger.
A merchant implementing keyed transaction lower interchange settings should build role-specific virtual-terminal screens rather than presenting every employee with one generic form containing dozens of optional boxes.
Reception or Sales Staff
Require the core CNP information the organization uses, such as accurate billing ZIP, address, genuine invoice/order reference, and correct transaction environment.
Accounts Receivable
Expose invoice, customer-account, tax, and PO/customer-code fields used to reconcile payments.
Making the virtual terminal invoice number field part of the standard A/R workflow can reduce both reconciliation problems and missing reference data.
B2B Commercial-Card Team
Expose enhanced-data fields supported by the gateway and processor. Confirm that those fields map downstream correctly rather than merely appearing in the user interface.
Recurring Billing Staff
Do not give employees a saved PAN and tell them to manually key it again each month. Use the supported tokenized credential-on-file process and the appropriate subsequent-transaction classification.
Keyed Entry Downgrade Prevention Checklist
For practical keyed entry downgrade prevention, confirm:
- A valid authorization was obtained.
- The correct CNP/MOTO/transaction environment was selected.
- Accurate AVS address data was submitted where appropriate.
- CVV was used appropriately for the initial CNP authorization.
- CVV was not retained after authorization.
- The invoice/order reference is genuine.
- Eligible commercial cards receive valid enhanced data.
- Sales-tax and customer-code values are accurate.
- Stored credentials use the processor’s supported framework.
- Recurring and other merchant-initiated transactions are classified correctly.
- The batch is submitted within applicable clearing requirements.
- Old authorizations are not casually reused.
- Staff never fabricate tax, invoice, PO, or customer data.
Good keyed entry downgrade prevention is mostly about eliminating avoidable transaction-quality errors. It cannot turn an ineligible card or transaction into an interchange program for which it does not qualify.
Credential-on-File: Repeat Charges Need Different Setup
A monthly repeat payment should not normally be treated as though the customer called in and freshly presented the card number every month.
Stored-credential frameworks distinguish an initial cardholder-involved transaction from subsequent charges initiated under the customer’s prior agreement. Recurring, installment, unscheduled credential-on-file, resubmission, and delayed-charge transactions should not simply be collapsed into one generic “saved card” category.
Correct classification can affect authorization messaging, issuer treatment, dispute evidence, and qualification.
Keep these concepts separate:
- Recurring payment
- Installment payment
- Unscheduled credential-on-file transaction
- Resubmission
- Delayed charge
They are not interchangeable descriptions for “we already have the card.”
For merchants optimizing card not present interchange requirements, this classification is just as important as collecting address or invoice information.
CVV and Stored Cards: Do Not Save the Security Code
CVV may be collected for an appropriate initial card-not-present authorization.
After authorization, PCI DSS prohibits retaining it. PCI SSC specifically states that card verification codes cannot be stored for card-on-file or recurring transactions.
Do not store CVV in:
- Customer notes
- Accounting software
- CRM records
- Spreadsheets
- Invoice PDFs
- Ticket systems
- Call recordings
PCI SSC also addresses the risks created when sensitive authentication data is captured in telephone recordings, which is especially relevant to MOTO businesses.
Tokenize the reusable credential instead of saving prohibited authentication data.
Invoice Numbers, Customer Codes, and Tax Data: Accuracy Matters
Enhanced-data fields are not decorative.
Bad values can create reconciliation errors, interfere with commercial-card data quality, and make transaction records harder to defend or audit later.
Avoid:
- Fake tax amounts
- Reused invoice numbers
- Generic “0000” customer codes
- Placeholder strings
- Item totals that do not reconcile
- Freight values that do not match the invoice
- Discounts unrelated to the actual transaction
The same principle applies to the virtual terminal invoice number field: requiring a field does not improve transaction quality if employees fill it with meaningless data simply to move to the next screen.
How to Spot Qualification Failures on a Merchant Statement
An interchange-plus statement is most useful when it exposes underlying interchange categories rather than only one blended rate.
Look for columns or reports showing:
- Card network
- Card/product type
- Interchange category
- Transaction count
- Sales volume
- Interchange cost
- Network assessments
- Processor markup
Then look for unexpected categories or sudden changes in volume.
Visa publishes categories including Standard and other product-specific programs within its U.S. schedule, while Mastercard publishes its own network-specific programs. The exact labels displayed on the merchant statement can still differ by processor.
This is where keyed entry downgrade prevention becomes measurable rather than theoretical. If a category suddenly increases after a virtual-terminal configuration change, the statement provides a starting point for identifying whether missing data, transaction type, authorization timing, or another factor changed.
When analyzing those charges, it also helps to separate actual network pass-through expenses from negotiable processor costs. This explanation of Visa APF, Mastercard NABU, and other pass-through statement fees provides useful context for making that distinction without assuming that every line item is an interchange downgrade.
If the processor reports only one effective percentage, reviewing why a merchant’s effective processing rate can differ from the quoted rate can also help separate transaction-mix effects from processor markup before beginning a deeper qualification audit.
Calculate What Downgrades Cost Per Month
Illustrative example—not an industry average:
Assume a merchant processes $250,000 per month in keyed transactions and identifies $40,000 that appears to be falling into a higher-cost category.
For illustration only, suppose the difference between the expected and actual categories is 0.50 percentage points.
Incremental Downgrade Cost = Downgraded Volume × Rate Difference
$40,000 × 0.50% = $200 per month
Annualized:
$200 × 12 = $2,400 per year
The 0.50% figure is hypothetical. The actual calculation should use the real interchange categories and costs shown on the merchant’s statement or qualification report.
Illustrative Downgrade Cost Calculation
| Measure | Example |
| Monthly keyed volume | $250,000 |
| Suspected downgraded volume | $40,000 |
| Illustrative rate difference | 0.50% |
| Monthly excess cost | $200 |
| Annualized excess cost | $2,400 |
At substantial transaction volume, even a relatively small qualification difference can justify investigating the relevant keyed transaction lower interchange settings.
Create a Downgrade Audit Table
| Statement Category | Volume | Expected Treatment | Rate Difference | Excess Cost | Likely Cause to Investigate |
| Category A | $15,000 | Normal CNP | Actual comparison | Calculate | Missing AVS/data |
| Category B | $10,000 | Commercial data | Actual comparison | Calculate | Enhanced fields missing |
| Category C | $8,000 | Stored credential | Actual comparison | Calculate | Generic keyed sale |
| Category D | $7,000 | Timely clearing | Actual comparison | Calculate | Late batch/capture |
The “likely cause” column is only a diagnostic hypothesis. Confirm the actual qualification reason with the processor or acquirer rather than assuming the virtual terminal caused the change.
A Two-Minute Monthly Qualification Check
For a clean interchange-plus statement, a first-pass review can be fast. Complex statements can require longer.
- Pull the latest merchant statement.
- Locate keyed/CNP interchange categories.
- Compare their volume with the prior month.
- Flag new Standard, EIRF, downgrade, or other unexpected categories.
- Check settlement exceptions.
- Review AVS utilization or missing-address reporting.
- Review commercial-card enhanced-data volume.
- Confirm recurring and stored-card transactions remain properly coded.
- Calculate the excess cost of material changes.
- Open a processor ticket when a category changes without an obvious operational reason.
This short review turns keyed entry downgrade prevention into a recurring financial-control process instead of a one-time configuration project.
Virtual Terminal Configuration Checklist
Transaction Fields
- Billing street address
- Billing ZIP
- Invoice/order number
- Customer/PO code
- Actual sales-tax amount
- Level II/III fields where supported and applicable
Fraud Controls
- AVS enabled
- CVV enabled for appropriate initial CNP transactions
- Reasonable velocity controls
- No CVV retention
Settlement
- Automatic batch close
- Correct timezone
- Verified processor cutoff
- Known weekend/holiday behavior
- Settlement-exception reporting
Credential on File
- Initial customer agreement or consent
- Tokenized stored credential
- Appropriate transaction indicators
- Recurring and unscheduled workflows separated
- No stored CVV
Staff Controls
- Mandatory fields
- Role-based permissions
- Saved workflows/templates
- Audit logs
- Restricted overrides
Reporting
- Interchange-category detail
- Qualification/downgrade report
- Settlement-exception report
- AVS reporting
- Commercial enhanced-data reporting where supported
These are practical keyed transaction lower interchange settings because they address the inputs and operational controls that can actually influence transaction qualification while avoiding the false promise that every keyed payment can reach the same rate.
Common Virtual-Terminal Qualification Mistakes
| Mistake | Why It Can Cost More | Better Control |
| Leaving ZIP optional | Creates incomplete address data | Require accurate billing data |
| Skipping AVS | Removes an important CNP verification input | Enable AVS where supported |
| Assuming CVV guarantees lower interchange | Confuses fraud control with qualification | Treat CVV primarily as authorization control |
| Closing batches late | Can create authorization/clearing issues | Automatic daily batching |
| Re-keying repeat cards monthly | Can misclassify repeat transactions | Tokenized credential-on-file workflow |
| Missing stored-card indicators | Transaction can be coded incorrectly | Use supported COF logic |
| Leaving commercial fields blank | Can prevent enhanced-data qualification | Require relevant B2B fields |
| Entering fake sales tax | Corrupts transaction data | Submit actual tax only |
| Wrong transaction type | Changes processing treatment | Role-specific workflows |
| Ignoring statement categories | Qualification leakage goes unnoticed | Monthly category review |
| Reviewing only processor markup | Misses interchange movement | Analyze network category and markup separately |
| Treating all keyed cards alike | Ignores card/network differences | Segment by product and transaction type |
FAQs
Does AVS lower interchange on keyed transactions?
Sometimes address data forms part of an applicable CNP qualification path, but AVS match interchange qualification is not a universal automatic rate reduction. AVS should first be understood as an authorization and address-verification control.
Does entering CVV get a better interchange rate?
Not universally. CVV is principally a card-not-present authorization and fraud-control element. Use it appropriately for an initial transaction, but do not assume it automatically changes interchange.
Should invoice number always be required?
It is an excellent reconciliation control for invoice-driven businesses and can be relevant to commercial enhanced-data workflows. Whether the virtual terminal invoice number field is technically required for a specific qualification program depends on the network, card product, gateway mapping, and processor.
Does same-day settlement lower interchange?
Timely clearing can help preserve qualification because authorization-to-clearing time can be a network criterion. However, same day batch settlement rates are not a universal interchange category. Verify the applicable network program and processor cutoff rather than assuming same-day batching always produces the lowest cost.
What causes keyed transactions to downgrade?
Possible causes include incomplete data, incorrect transaction indicators, authorization issues, late clearing, missing commercial-card information, gateway mapping problems, or ineligibility for the expected interchange program.
Can Level II or Level III data lower commercial-card costs?
Eligible commercial-card transactions can qualify differently when valid enhanced information is transmitted through the supported processing path. The transaction must still meet the applicable network and card-product requirements.
Do Level II or Level III fields help consumer cards?
Generally, enhanced commercial-card information is relevant to eligible commercial products, not ordinary consumer-card qualification.
Can I store CVV for repeat virtual-terminal charges?
No. PCI DSS prohibits retaining card-verification codes after authorization, including for recurring or credential-on-file transactions.
Should repeat charges be keyed manually?
A supported stored-credential workflow is generally more appropriate. It maintains the distinction between the initial credential setup and subsequent recurring or other merchant-initiated transactions.
How can I tell whether my keyed transactions are qualifying correctly?
Review an interchange-plus statement or processor qualification report by network, card type, interchange category, volume, and cost. Then investigate unexpected categories with the processor rather than assuming that every higher-cost line represents the same type of downgrade.
Configure the Virtual Terminal Around Qualification, Not Convenience
Effective keyed transaction lower interchange settings are really a coordinated set of transaction controls:
- Capture accurate CNP authorization data.
- Make appropriate fields mandatory.
- Submit valid enhanced data on eligible commercial cards.
- Use correct stored-credential indicators.
- Clear transactions within applicable network and processor requirements.
- Audit interchange categories every month.
The goal is not to make every field mandatory for every transaction. It is to align the virtual terminal with the applicable card not present interchange requirements, eliminate avoidable data omissions, enforce accurate transaction classification, and make keyed entry downgrade prevention part of normal payment operations.
Use current network documentation when validating these controls rather than relying on old interchange charts or generic processor claims. Visa’s current U.S. interchange schedule documents network-specific categories and commercial programs. Visa U.S. interchange reimbursement fees Mastercard separately explains its qualification criteria and maintains its own current interchange resources.
Lower interchange on keyed volume is usually the result of correct transaction classification, complete and truthful data, and disciplined settlement—not one magic field or checkbox.